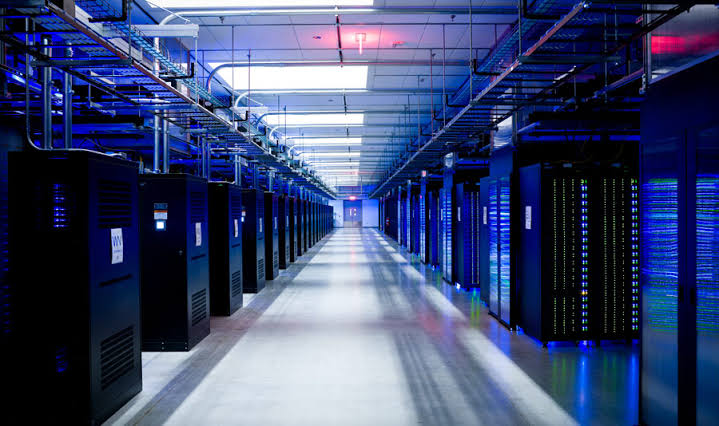
Data centers are a critical infrastructure and as of recent, there has been an increased demand due to the AI’s growth. Data centers are a great investment opportunity with guaranteed returns. Having advised on several transactions involving data centers in Africa, several critical questions come to mind:
- Are Governments renting sovereignty to big tech?
It is no secret that the largest data centers and cloud services are owned and controlled by big tech companies outside of the Africa continent. Obviously there are security measures installed to protect the data stored but the risk of breaches and unauthorized access are still lurking in the shadows. African Governments are actively embracing technology and most Government’s operations are now undertaken online in most jurisdictions from company incorporation, to licensing, to storage of data by Ministries and other Government institutions. However, due to shortage of data centers within African countries, Governments are forced to use data centers and cloud services owned and managed by big tech non-resident companies. This means that, the data is stored outside of the country, and can be accessed by third parties (legally or illegally). This poses a risk on national security, among other issues. There are always assurances of protection of data from big tech companies but the risk remains that, there is little Governments can do if there is a breach or unauthorized access, where even financial compensation is not adequate to cure the serious consequences of theft of data.
- Data localization laws vs economic reality
Several African countries require data generated in sensitive sectors such as banking, mining, and telecommunications to be stored locally, largely to protect national interests and strengthen regulatory oversight. While the policy intent is admirable, implementation often runs ahead of infrastructure. In many African markets, there are limited or no local data centers capable of meeting the operational, security, and resilience needs of modern businesses.
This creates a practical dilemma for companies whose core business is not building or managing digital infrastructure. Establishing compliant data centers is capital-intensive and technically complex, and in smaller or fragmented markets the economics rarely make sense. Without parallel investment in local data center capacity or regional solutions, data localization risks becoming a cost burden rather than a catalyst for digital growth, potentially slowing investment and innovation instead of enabling them.
- Is Africa energy and water sector at par with needs of data centers
It is undisputed that data centers are energy hungry, and with the rapid expansion of AI, many African countries currently lack the capacity to sustainably meet their energy and water requirements. In most markets, the energy sector remains fragile, with domestic demand still unmet, even before factoring in the additional load created by data centers. This places governments in a difficult position, as prioritizing energy supply for data centers can be hard to justify where local industries, businesses, and households continue to experience unreliable or limited access to electricity.
In addition, data centers require significant volumes of water for cooling, yet access to clean and safe water remains limited for large segments of the population across the continent. This challenge is further compounded by increasing climate stress in Africa, driven by environmental degradation and global warming. Against this backdrop, the question is not only whether data centers can be supported, but whether energy and water systems are being strengthened in a way that balances digital growth with broader social, and environmental needs.
- Data centers are still privately owned
While some African governments have established data centers to support public sector operations, these facilities often struggle to meet even internal government demand, let alone the needs of private sector users. This raises practical questions about whether state-owned data centers can realistically serve as shared infrastructure for the wider economy. From the private sector’s perspective, concerns around data security, independence, and operational reliability may limit willingness to rely on government-run facilities. As a result, even where governments invest heavily in data centers, attracting sustained private sector uptake can be challenging unless clear governance frameworks, commercial models, and trust mechanisms are in place.
- Data centers without governance
For private companies looking to invest in data centre infrastructure in African countries, a key challenge is the lack of clear governance frameworks, including supportive policies, well-defined laws, and predictable regulatory processes. While technology, AI, and digital infrastructure are evolving rapidly, regulatory development across much of Africa has not kept pace, creating uncertainty for investors. This challenge is compounded by a shortage of skilled technical experts, driven in part by brain drain and limited investment in the local technology ecosystem, including research and development. Together, these gaps make it harder to attract and retain long-term, high-quality investment in data centre infrastructure.
Conclusion
Africa was once known mainly as an exporter of raw materials. Today, it is increasingly an exporter of data, which has become a new form of wealth. A small number of technology companies have begun to explore investment in data centers across the continent, but many have faced practical challenges, including complex licensing processes, limited access to suitable land, and unreliable energy supply. We now live in a data-driven world, where control over data also means influence over economic and strategic resources. At present, this power is largely concentrated in the United States, Europe, and China, with Africa once again playing a limited role. If African countries want to change this position, data centers must be treated as strategic and geopolitical assets, not just technical infrastructure. This requires deliberate efforts to attract investment, supported by clear policies, reliable energy planning, and regulatory frameworks that give investors’ confidence while serving broader national interests.
Disclaimer
The views expressed in this paper are those of the author only and should not be considered as an official interpretation, defamatory, or interference of any legislation, laws, or policies of any country including Tanzania. The contents of this paper should not under any circumstances be reproduced or used without the express written consent of the Author. It should not be considered as legal advice to any of its recipient(s) and should not be relied upon without obtaining further legal advice. We accept no liability for any loss occasioned or suffered due to the contents of this paper. The information contained herein is general and is not intended to address the circumstances of any particular deal. Although effort has been made to research and share the correct information, we do not provide any guarantee to such information.